

Avant
4.7

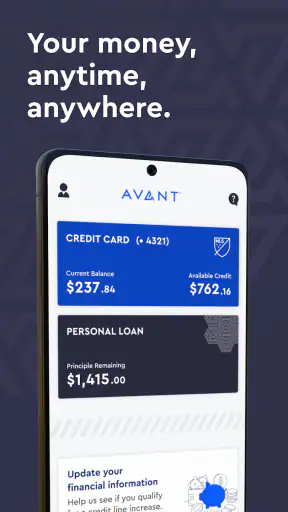
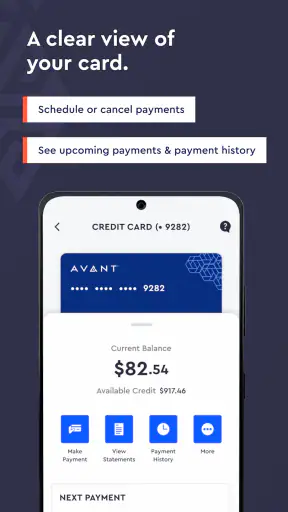
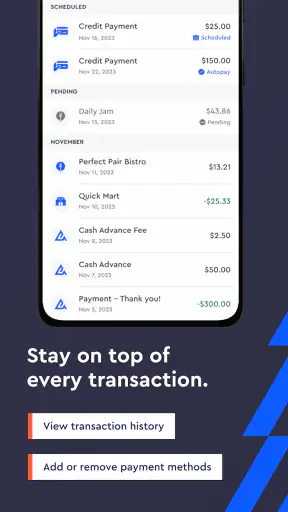
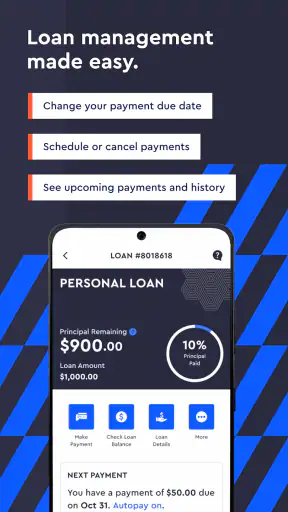
I spent time using Avant as a finance app, and my overall impression is that it is built for people who want a straightforward place to handle an Avant card or loan from a phone. The focus is practical rather than ambitious: checking transactions, making payments, and keeping an eye on an existing account without needing to switch to a desktop browser.
That narrow purpose is important. This is not the kind of money app I would choose as a complete household budget, investment dashboard, or general banking replacement. Its usefulness depends on already having a relationship with Avant, LLC. If that describes you, the app can put the most relevant account actions close at hand. If it does not, there is little reason to install it simply because it is free.
What the Avant app is designed to do
The app belongs to the finance category and is aimed at account management rather than financial education. In everyday use, I would open it when I wanted to review recent activity, make a payment, or check details connected with an Avant card or loan. That makes it more of a companion to an existing financial product than a standalone tool for organizing every part of my finances.
The developer is Avant, LLC, which gives the app a clear connection to the card and loan services it is meant to support. The store summary points to payments and transactions, and that matches the way I would expect to use it: short visits with a specific task in mind, not long sessions exploring a large collection of tools.
The current version is 4.7.0 and it runs on Android devices using version 6.0 or later. The app is free to download and carries an Everyone age rating. Those details make the basic entry barrier low, although free installation should not be confused with free borrowing or with the absence of any terms attached to a separate card or loan agreement.
That distinction is the most important cost point. I can access the application without paying for the download, but the app itself does not turn an Avant financial product into a cost-free product. Any interest, fees, payment obligations, or other account terms belong to the relevant card or loan agreement, not to the simple act of installing the application. I would read those terms carefully before treating the app as evidence that borrowing is inexpensive.
A useful companion for quick account tasks
The strongest part of the experience is the directness of the workflow. When I am checking whether a payment has been reflected or trying to understand a recent transaction, a dedicated account app is more convenient than searching through email, opening a general banking site, or calling support for information that should be visible on screen. Avant keeps the attention on the account rather than surrounding it with unrelated financial products.
I also like the mental separation this creates. A general budgeting app may bring together checking accounts, credit cards, subscriptions, and savings goals, but that broader view can make one specific payment harder to find. With an Avant-focused app, the task is clearer: open the account, inspect the activity, and deal with the next payment-related action.
One practical habit I would recommend is checking transactions before making a payment rather than immediately tapping the payment option. That small pause can help distinguish a posted purchase from a payment that is still processing, and it gives me a better picture of what the account is showing at that moment. It is a simple workflow, but it reduces the chance of making decisions based on an incomplete glance.
A second useful habit is to treat the transaction view as a regular review point, not only as a place to investigate a problem. Looking through activity after a purchase or before a due date can make unfamiliar entries easier to recognize. It is also a more reliable routine than trying to reconstruct account activity from memory or from scattered notifications.
How it fits into an ordinary day
Imagine I have used an Avant card for a household purchase and want to confirm the transaction later that evening. I can open the app, review the account activity, and return when I am ready to make a payment. On a busy morning, that is more useful than logging in from a computer just to perform one small task. The app earns its place through these short, repeatable interactions.
The same applies to a loan account. A person who wants to keep payment activity visible on a phone may prefer a dedicated interface over paper records or a browser bookmark. The benefit is not that the app changes the underlying loan; it is that the account is easier to check while moving through a normal day.
For this reason, I would judge the app by how quickly it helps me answer focused questions: What activity is showing? Has my payment appeared? What do I need to do next? A finance app does not need to be packed with extras to be useful, but its core account information needs to be easy to reach and easy to interpret.
Value, limitations, and the cost of choosing a focused app
The app has a strong value proposition for an existing Avant customer because the download is free and the main actions are closely tied to that customer’s account. I am not paying separately for a budgeting suite that I may never use. Instead, I get a mobile route to the card or loan tasks that matter to me.
That value is conditional, though. Free access to the app is not the same as free access to credit. If I am comparing borrowing options, I would compare the actual agreement, repayment schedule, and total cost rather than deciding from the app’s download price. The application can make management more convenient, but convenience should not be mistaken for a better financial deal.
There is also a trade-off between focus and breadth. A dedicated Avant app can be less distracting than a full-service banking platform, but it will not replace a tool that shows my entire financial life in one place. If I need spending categories across several institutions, savings targets, investment tracking, or a combined household view, I would look at a broader finance service instead.
This is where some users may feel the app is limited even if it performs its main role well. A person who wants detailed planning tools may open it expecting a complete money-management center and find that its purpose is much narrower. I would not call that a flaw by itself, but it is a reason to set the right expectation before downloading it.
Another trade-off is dependence on the underlying Avant relationship. The app’s usefulness is tied to the account it manages. Someone without an Avant card or loan is unlikely to gain meaningful value from it, while an existing customer may find it much more relevant than a generic finance app. That difference matters more than the download being free.
Where it compares well with common alternatives
Compared with a mobile browser, a dedicated app usually makes repeated account checks feel more intentional. I do not have to search for the correct page each time, and the experience is centered on the account rather than on a website’s wider navigation. For a task I perform regularly, that reduction in friction is worthwhile.
Compared with a general banking app, Avant has the advantage of specialization. A broad banking application may be better for checking a deposit account, transferring money, and reviewing several products together, but it may not be the clearest place to manage an Avant-specific card or loan. The focused app gives that relationship its own space.
Compared with a budgeting application, the difference is even clearer. Budgeting tools are useful when I want categories, trends, goals, and a wider spending picture. Avant is more appropriate when the immediate need is account servicing. I would use both only if I wanted the dedicated account access of Avant alongside a separate system for broader financial planning.
The best alternative therefore depends on the job. For a single Avant account, the official app is the more natural choice. For a complete view of multiple accounts, another tool may be better. For occasional access, a browser may be sufficient. I would not choose one option simply because it has more features; I would choose the one that matches the action I actually need to perform.
Small workflows that make it more useful
My first recommendation is to make account review part of a payment routine. Rather than opening the app only after something looks wrong, I would check the recent activity before scheduling or submitting a payment. This creates a clear sequence: review, confirm, then act. It is especially helpful when several transactions have occurred since the last account check.
My second recommendation is to use the app as a verification point after an important account action. If I make a payment, I would return later to review the activity instead of assuming that the process is complete because I tapped a button. The app is most valuable when it helps me maintain an accurate picture of the account over time.
My third recommendation is to keep the app’s role separate from a personal budget. I would not rely on transaction visibility alone to decide whether I can afford a purchase. Instead, I would use the account information as one input, then compare it with my wider spending plan and other obligations. This avoids the common mistake of treating an account-management screen as a full financial plan.
These workflows also show the app’s limits. It can support awareness and routine servicing, but it cannot make a borrowing decision for me or replace careful reading of account terms. The convenience is real, yet the responsibility for understanding the financial product remains with the account holder.
Who is likely to get the most value
I would recommend Avant to an existing cardholder or loan customer who prefers handling routine account tasks from a phone. The app is particularly suitable for someone who checks transactions regularly, wants a convenient payment route, and does not need a large collection of budgeting or investment features in the same interface.
It may also suit people who dislike using a browser for every account visit. A dedicated app can make a repeated task feel quicker and more organized, especially when the goal is simply to inspect activity or manage a payment. The free download makes trying that workflow straightforward, provided the device meets the Android requirement.
I would be more cautious if someone is still deciding whether to take out a card or loan. In that situation, the app should not be the reason to choose the product. I would compare the financial terms first and treat the app as a management convenience that comes afterward. A polished account interface cannot compensate for borrowing that does not fit a person’s budget.
I would also point people toward a different option if their main goal is comprehensive money organization. Someone managing several banks, shared household expenses, investments, or detailed savings goals will probably need a broader finance platform. Avant can sit beside that kind of tool, but I would not expect it to replace one.
Reliability, trust, and what to check before committing
The app has an average rating of 4.7 from around fifty-eight thousand ratings, with roughly five thousand reviews, and it has passed half a million installs. That level of adoption suggests that many people are using it for the intended account-management purpose. I still would not treat popularity as proof that every experience will be identical, because account access and payment situations can vary from one customer to another.
When using any finance app, I prefer to verify important account actions rather than relying on a single screen. I would review the transaction details, keep track of payment timing, and retain any confirmation information that matters to me. Those habits are useful here because the app is a tool for managing an existing financial obligation, not a substitute for personal records.
The Everyone rating is reassuring for general accessibility, but age suitability is not the same as financial suitability. A young or inexperienced user may still need help understanding credit, repayment, and the consequences of missed payments. The app can present account information, but it cannot replace responsible guidance when the underlying product is unfamiliar.
My main criticism is therefore not that the app tries to do too little; it is that some users may expect more from it than it is designed to provide. The focused approach is convenient for Avant customers, yet it can feel incomplete beside all-in-one banking and budgeting products. I would rather see that limitation clearly than download it expecting a financial command center.
My final recommendation
For an existing Avant customer, I think the app is an easy recommendation. It is free to download, focused on practical card and loan management, and suited to quick checks and payment-related routines. The strongest value comes from reducing everyday friction, not from adding a sophisticated planning system.
For someone without an Avant account, I would skip it. There is no good reason to install a relationship-specific finance app merely because the download costs nothing. I would first choose the financial product that fits my circumstances, then use the app if it offers the account access I need.
My final view is that Avant is best understood as a convenient account companion, not a complete personal-finance solution. I would use it for transaction awareness and routine payments, while keeping a separate budget and reading the underlying card or loan terms carefully. That combination gives the app a clear, useful role without asking it to solve problems outside its purpose.
If your priority is simple mobile access to an Avant card or loan, the app delivers sensible value at no download cost. If your priority is broad financial planning, multi-account tracking, or deciding whether borrowing is affordable, I would choose a different tool for those decisions and keep Avant limited to the account tasks it handles most naturally.
4.7
5.41K Reviews
Pros
- Clean interface makes browsing and managing content straightforward.
- Quick access to core features keeps everyday use convenient.
- Runs smoothly on most modern Android and iOS devices.
- Useful settings let users adjust the experience to their preferences.
- Regular updates can improve stability and add helpful refinements.
Cons
- Some advanced features may require payment or a subscription.
- The app may feel limited if you expect extensive customization options.
- Performance can vary on older devices or slower connections.
- Certain functions may depend on account registration or permissions.
- Support and troubleshooting options may be limited for some issues.


